Navigating debt can be challenging, and many people look to debt relief programs as a potential lifeline. These programs can offer hope and a path to financial recovery, but they don’t produce the same results for everyone. A debt relief program’s effectiveness can vary based on several factors, including the type and amount of debt, the creditors involved, individual financial situations, and the chosen strategy.
If you’re wondering whether debt relief programs can truly make a difference, they might work under the right circumstances. Take the time to understand how these programs work, what you’ll need to commit to, and any potential risks or limitations. By doing so, you’ll be better equipped to make an informed decision about your financial future.
Are Debt Relief Programs Legit?
Some debt relief programs are legitimate, but consumers should still evaluate providers carefully.
A legitimate debt relief company should clearly explain its services, fees, eligibility requirements, and possible risks. Consumers should be cautious of companies that promise a specific amount of savings, guarantee that creditors will agree to settlement terms, or claim that debt can be resolved within a fixed period.
The question “Are debt relief programs legit?” also depends on the type of program being considered. Debt consolidation, debt management, and debt settlement are different approaches, and each has different requirements.
For example, debt consolidation generally involves combining multiple debts into a single loan or payment. Consumers comparing programs may want to review the different types of debt consolidation before choosing an option.
How Debt Relief Programs Are Supposed to Work
Debt relief programs are designed to help eligible consumers manage or resolve debt under different terms.
The process depends on the program. A debt consolidation loan may replace several balances with one new loan. A debt management plan may organize payments under a structured repayment schedule. Debt settlement may involve negotiating with creditors to resolve eligible debts for less than the full amount owed.
Consumers considering consolidation should understand what debt consolidation is and how to consolidate debt before moving forward. No matter which type of program is used, results generally depend on participation from both the consumer and, in some cases, creditors.
What Debt Relief Program Success Rates Actually Show
Debt relief program success rates can be difficult to compare because providers may define success differently. One company may consider a debt successfully addressed once a settlement agreement is reached. Another may measure success only after a consumer completes the entire program. Some statistics may also apply only to consumers who remained enrolled for a certain period.
For that reason, a single debt relief program success rate does not necessarily indicate what will happen in an individual case. Consumers should review how any success rate is calculated, what types of debt were included, and whether the reported results reflect all enrolled clients or only completed cases.
At United Settlement, our client success stories are examples of individual experiences, but past results don’t guarantee similar outcomes for other clients.
Factors That Determine Whether It Works for You
Several factors can affect whether a debt relief program works in a particular situation. These may include:
- The total amount and type of debt
- Whether the debt is eligible for the selected program
- Income and monthly expenses
- Ability to make required program payments
- Creditor participation
- Credit history and current credit profile
- Changes in income or financial circumstances
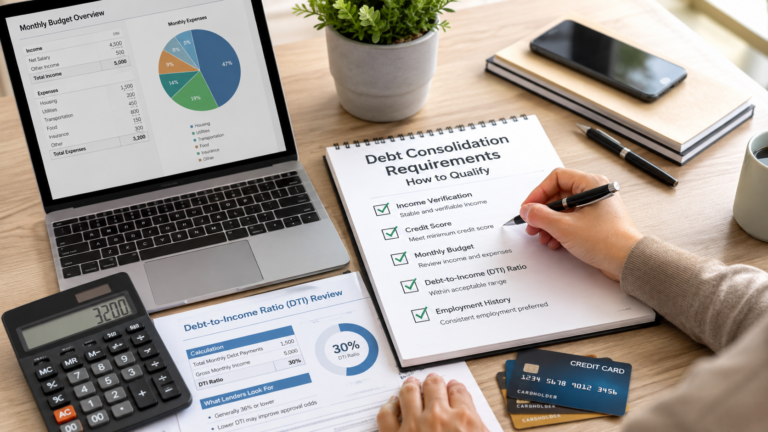
Some programs also have specific qualification requirements. For example, consumers considering consolidation can review common debt consolidation requirements before applying.
Understanding these factors can help determine whether a particular debt relief option is realistic.
When Debt Relief Programs Don’t Work
Debt relief programs may not work if a consumer cannot meet the program requirements or if the selected approach doesn’t match the type of debt involved.
For example, a borrower may struggle to qualify for a consolidation loan if they have limited income or a low credit score. A settlement program may not produce an agreement if a creditor chooses not to participate. A repayment plan may become difficult to maintain if income decreases or unexpected expenses increase.
Consumers should also consider the possible effect on credit. Different debt relief strategies may affect credit in different ways. Those considering consolidation can review how debt consolidation may affect credit before deciding whether it fits their needs.
Who Debt Relief Programs Actually Work Best For
Debt relief programs may be more appropriate for consumers with significant unsecured debt who are struggling to keep up with their existing payment obligations. They may also help people with enough income to participate in a structured plan but who need different repayment terms.
The appropriate solution depends on individual circumstances. Some consumers may qualify for consolidation, while others may be better suited to a debt management or settlement program. Before moving forward, compare benefits and limitations of each approach and decide whether debt consolidation makes sense for your situation.
Does Debt Relief Work? The Honest Answer
So, does debt relief work? In some cases, yes. However, debt relief should not be viewed as a guaranteed way to eliminate debt or achieve a specific financial outcome.
Consumers asking “Do debt relief programs work?” should focus on whether a program fits their debt, income, and ability to meet its requirements.
Before enrolling, review the terms carefully, understand the possible risks, and ask how fees are charged. Depending on the circumstances, it may also be appropriate to speak with a qualified financial, tax, or legal professional.
United Settlement can review a consumer’s financial situation and explain which debt relief options may be available. Eligibility, settlement results, savings, and program timelines vary by individual case, and no specific outcome can be guaranteed.
Steven Brachman is the lead content provider for UnitedSettlement.com. A graduate of the University of Michigan with a B.A. in Economics, Steven spent several years as a registered representative in the securities industry before moving on to equity research and trading. He is also an experienced test-prep professional and admissions consultant to aspiring graduate business school students. In his spare time, Steven enjoys writing, reading, travel, music and fantasy sports.